The Complete Configuration Blueprint for Sony Pictures CEO Tony Vinciquerra to step down, succeeded by Ravi Ahuja
 androfyi
September 25, 2026
7 min read
15 views
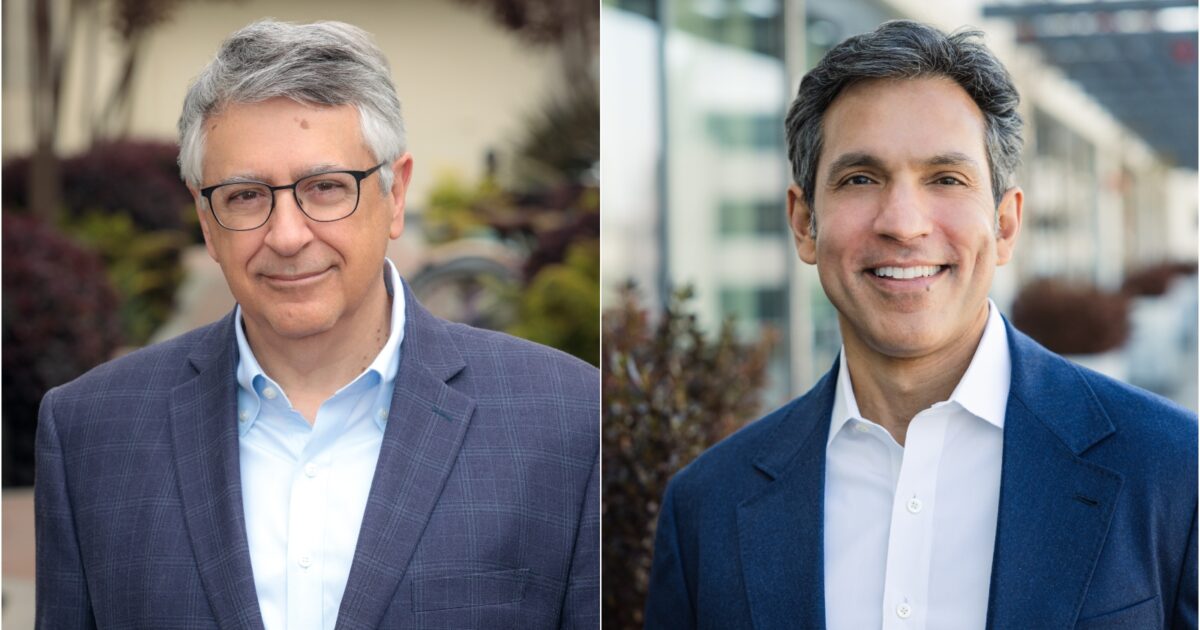
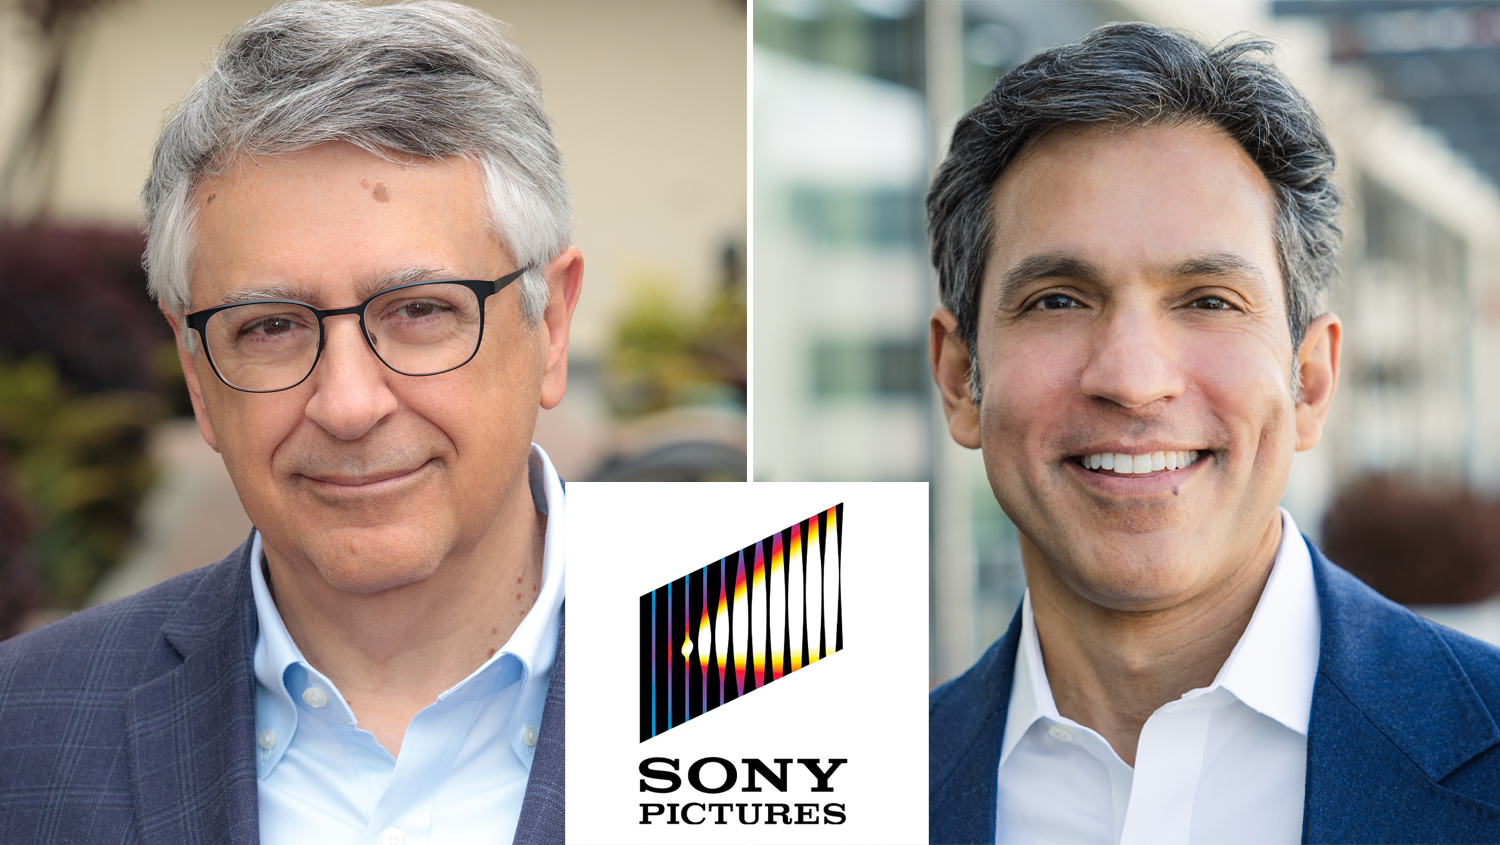
Here’s what most analysts are missing in the noise: Sony Pictures Entertainment isn’t just swapping one suit for another. This is a surgical infrastructure upgrade disguised as a personnel announcement. Tony Vinciquerra spent seven years pulling SPE back from the brink of irrelevance – slashing dead-weight cable assets, dodging the streaming money-pit that swallowed competitors whole, and quietly engineering a profit machine that survived a pandemic and a dual writers-actors strike. Now he’s handing the keys to Ravi Ahuja, a guy whose resume reads like a checklist of every operational weakness Hollywood desperately needs fixed. The market wants to frame this as a standard executive succession. Our team sees a deliberate recalibration of the entire production-to-profit pipeline. This guide unpacks every hidden parameter in that transition.
The Pre-Flight Checklist
- Core Infrastructure: SPE’s current five consecutive years of profit growth under Vinciquerra, built on cable divestiture and a disciplined avoidance of the general entertainment streaming trap
- Succession Timeline: January 2, 2025 for Ahuja’s formal takeover, with Vinciquerra retained as non-executive Chairman through December 2025 for advisory continuity
- Reporting Matrix: Ahuja reports to Sony Group Corporation Chairman and CEO Kenichiro Yoshida and President/COO/CFO Hiroki Totoki – meaning Tokyo’s oversight layer remains intact, not decentralized
- M&A Backlog: Industrial Media, Bad Wolf, and Pixomondo acquisitions already executed under Ahuja’s watch; GSN Games divestiture to Scopely signals continued portfolio surgery
- Content Pipeline: The Crown, The Boys, Cobra Kai, The Last of Us, Better Call Saul, Shark Tank, and Jeopardy! represent the existing asset base Ahuja inherits
- Personnel Risk: Ahuja’s tenure at SPE is only three years – short enough that untested cultural fault lines remain beneath the surface
Phase One Execution
Let’s be blunt about what Vinciquerra actually configured during his seven-year tenure. When he arrived in June 2017, SPE was a bloated operation bleeding value through international cable networks and a film slate that couldn’t find consistent commercial footing. His first major system command was a hard divestiture of most cable assets – a move that looked like retreat to outsiders but was actually a deliberate offloading of depreciating infrastructure before the streaming bloodbath made those assets unsellable. He then made the Crunchyroll acquisition in 2021, which looked like a streaming play on paper but was actually a targeted IP grab in the one vertical where SPE could actually dominate: anime. While every other studio burned billions building general entertainment streaming services destined for chronic losses, Vinciquerra kept SPE out of that race entirely. That discipline is the single most undervalued decision in modern Hollywood strategy. It’s also the reason SPE remained profitable during COVID-19 and the 2023 SAG-AFTRA/WGA strikes while competitors hemorrhaged cash.
Now Ahuja inherits this lean machine. But lean machines require different operators than the bloated ones they replace. His background – President of Business Operations and CFO at Walt Disney Television, CFO at Fox Networks Group, and Virgin Entertainment Group – tells us exactly what Tokyo wants: someone who understands the P&L plumbing, not just the glamorous production side. His promotion to COO for the entire studio in April 2024 was the test run. The fact that the succession announcement followed five months later means Tokyo’s board ran that test and approved the results. That’s not sentimentality – it’s a verification protocol.
Step 2: Hidden Parameter Adjustments
Here’s the configuration nuance nobody’s talking about yet. Ahuja doesn’t just inherit a profit machine – he inherits a profit machine with very specific structural tensions that Vinciquerra managed but never fully resolved. First: SPE’s M&A strategy under Ahuja’s direct oversight has been aggressive on the production side (Industrial Media for unscripted, Bad Wolf for UK drama, Pixomondo for VFX) but there’s no equivalent investment in direct-to-consumer distribution. That means SPE remains a pure-play content supplier in an era where the most valuable entertainment companies control their own shelf space. Crunchyroll is the exception, not the rule. If Ahuja doesn’t build or buy a broader DTC platform, SPE’s long-term margin ceiling remains capped by whatever licensing deals it can extract from Netflix, Amazon, and Apple.
Second: the India business. Ahuja oversaw SPE’s India operations from day one, which suggests Tokyo sees that market as a critical growth vector. But India’s entertainment infrastructure is notoriously fragmented, with pricing pressure that makes Western market economics look luxurious. If Ahuja over-indexes on India expansion at the expense of margin discipline, the profit trajectory Vinciquerra built could flatten within 18 months.
Third: the advisory role itself. Vinciquerra as non-executive Chairman through December 2025 is not a graceful retirement. That’s a 12-month dead-man’s-switch on Ahuja’s autonomy. If Ahuja’s first year produces missteps, Vinciquerra’s institutional knowledge and board-level relationships create an implicit override mechanism. Every decision Ahuja makes in 2025 is being benchmarked against a ghost. That’s a hidden parameter that will shape every strategic call he makes in the first term.
Step 3: Advanced Automation Rules
The advanced configuration here involves understanding how SPE’s production-to-revenue automation actually functions under new management. Ahuja’s operational background means he’ll likely implement tighter financial controls on greenlighting decisions – something Vinciquerra’s more intuitive, relationship-driven approach didn’t always enforce at the project level. The practical impact: mid-budget films and series that relied on Vinciquerra’s personal advocacy rather than pure ROI calculation will face higher scrutiny thresholds. That could mean fewer passion projects but also fewer expensive write-offs.
The other automation rule involves content licensing windows. SPE under Vinciquerra was notably disciplined about holding content for maximum licensing value rather than dumping it onto platforms for quick cash. Ahuja’s CFO instincts may pressure faster monetization – especially if Tokyo’s corporate dashboards start demanding quarterly revenue acceleration. If Ahuja compromises the windowing strategy, the short-term numbers will look great and the long-term asset value will erode. Our team will be watching SPE’s licensing deal structures in Q2 2025 as the earliest signal of which configuration Ahuja actually prefers.
What Most Guides Tell You To Ignore (But Shouldn’t)
- Five consecutive years of profit growth provides a stable foundation for transition
- Disciplined M&A track record (Industrial Media, Bad Wolf, Pixomondo) shows Ahuja can execute without overpaying
- COVID-19 and dual-strike survival proves operational resilience
- No general entertainment streaming service means no massive ongoing loss center to manage
- Crunchyroll provides a vertical-dominant DTC asset with global growth runway
- Three-year tenure at SPE is insufficient to predict long-term cultural leadership
- No direct-to-consumer platform beyond Crunchyroll creates structural margin ceiling
- India operations add complexity and pricing pressure without guaranteed scale returns
- Advisory overlap with Vinciquerra creates dual-power dynamic that slows decision velocity
- Hollywood’s theatrical market remains structurally uncertain post-2023 strikes
- Reliance on third-party streaming platforms (Netflix, Amazon) for distribution leverage decreases negotiating power over time
The configuration most observers will miss entirely is the reporting structure itself. Ahuja reports to both Yoshida and Totoki – not just the Chairman. That dual reporting line means Sony Group’s corporate governance layer is tightening its grip on SPE’s operational independence. Vinciquerra enjoyed a wider latitude because he arrived during a crisis that demanded autonomy. Ahuja arrives during stability, which means Tokyo’s oversight sensors are calibrated to detect deviation, not empower improvisation. If Ahuja wants to make a bold, unconventional play – a major acquisition, a new streaming initiative, a dramatic slate restructuring – he’ll need to navigate two layers of corporate approval instead of one. That’s not a succession. That’s a constraint upgrade.
Tags: Sony Pictures Entertainment CEO succession, Tony Vinciquerra steps down, Ravi Ahuja Sony Pictures president, Sony Pictures leadership change 2025, Crunchyroll acquisition SPE, Sony Pictures M&A strategy, Hollywood studio executive transitions, Sony Group Corporation entertainment division, Ravi Ahuja Walt Disney Fox background, SPE cable network divestiture, Sony Pictures profit growth strategy, anime streaming market Sony, Bad Wolf Industrial Media Pixomondo acquisitions, SPE India business operations, Kenichiro Yoshida Sony Group leadership
